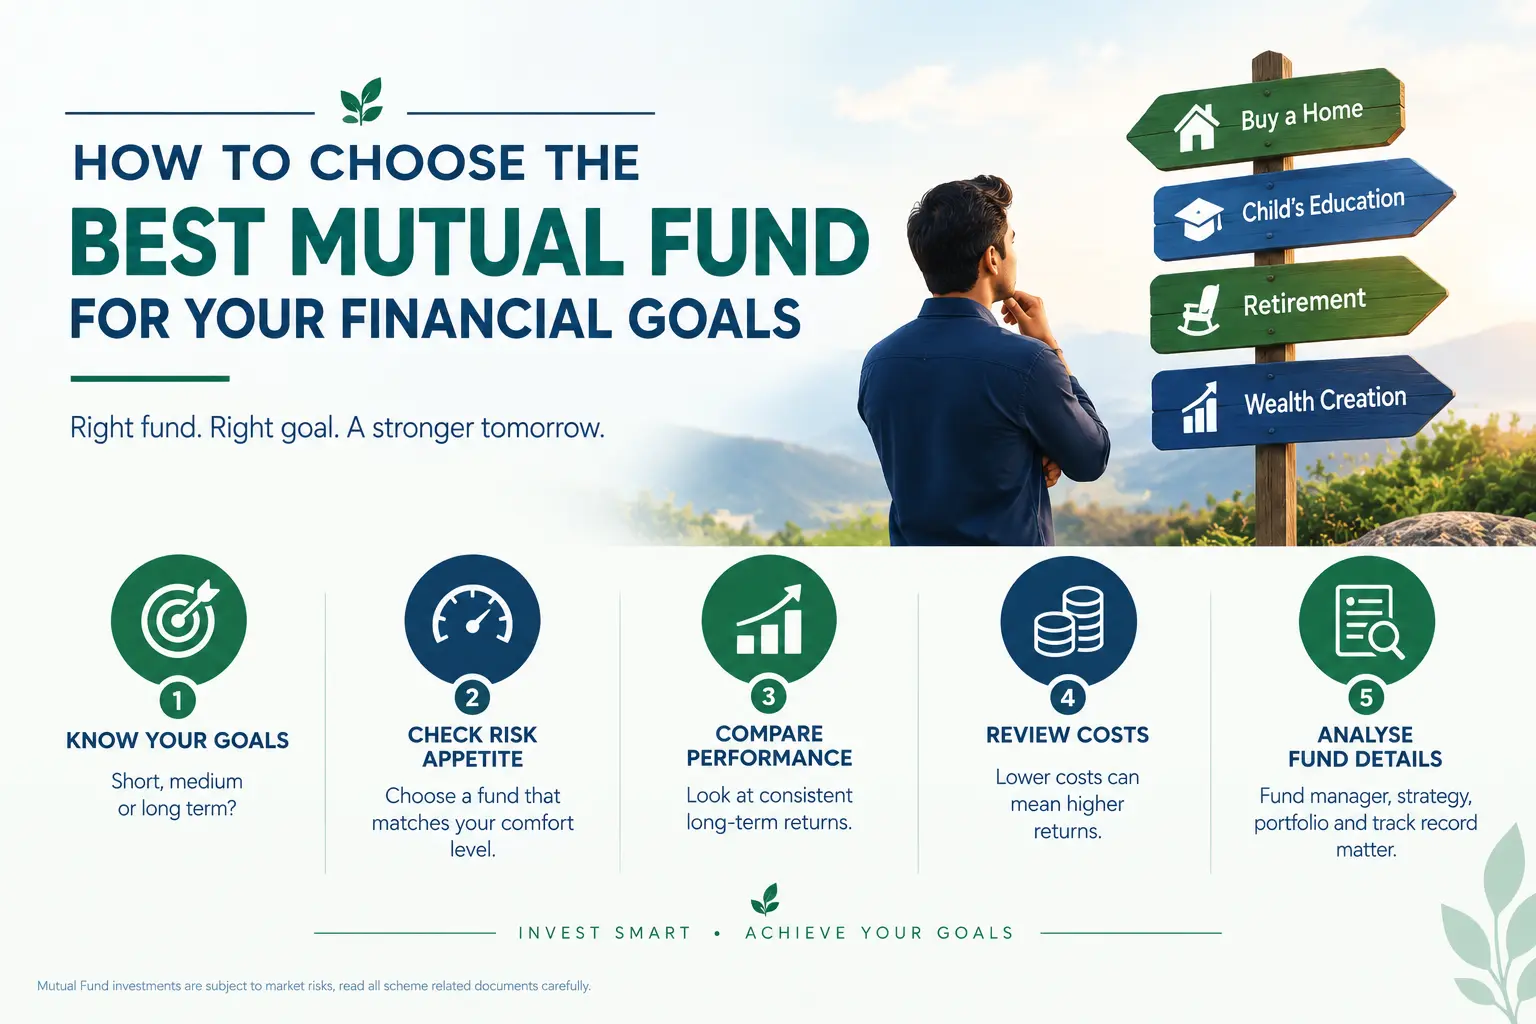
How to Choose the Best Mutual Fund for Your Financial Goals
How to Choose the Best Mutual Fund for Your Financial Goals
With thousands of mutual fund schemes available in India, choosing the right one can feel overwhelming. Every fund promises growth, but the best mutual fund isn't necessarily the one with the highest past returns—it's the one that aligns with your financial goals, investment horizon, and risk tolerance.
Whether you're investing for your child's education, retirement, buying a home, or simply building long-term wealth, selecting the right mutual fund requires a structured approach rather than chasing short-term market trends.
Here's a practical guide to help you make an informed investment decision.
Step 1: Clearly Define Your Financial Goals
Before selecting any mutual fund, ask yourself one important question:
Why am I investing?
Different financial goals require different investment strategies.
Some common goals include:
- Building long-term wealth
- Creating an emergency fund
- Saving for a child's education
- Planning for retirement
- Buying a house
- Tax saving under Section 80C
- Generating regular income
When your investment objective is clear, selecting the appropriate mutual fund becomes much easier.
Step 2: Determine Your Investment Horizon
Your investment duration plays a significant role in deciding which type of mutual fund is suitable.
Short-Term Goals (Up to 3 Years)
For goals that require money within a few years, relatively lower-risk options such as liquid funds or certain short-duration debt funds may be appropriate.
Medium-Term Goals (3–5 Years)
Hybrid funds, which invest in both equity and debt, may offer a balance between growth potential and stability.
Long-Term Goals (More Than 5 Years)
For long-term wealth creation, equity mutual funds have historically offered the potential for higher returns, although they are also subject to greater market volatility.
Long investment horizons generally provide more time to navigate market fluctuations.
Step 3: Understand Your Risk Appetite
Every investor has a different comfort level with market volatility.
Ask yourself:
- How would I react if my investments temporarily declined in value?
- Am I comfortable taking higher risks for potentially higher long-term returns?
- Do I prefer stability over growth?
Generally:
- Conservative investors may prefer debt funds.
- Moderate investors may consider hybrid funds.
- Aggressive investors with long-term goals often choose equity funds.
Choosing investments that match your risk tolerance can help you remain invested during market ups and downs.
Step 4: Understand Different Types of Mutual Funds
Each category serves a different investment objective.
Equity Mutual Funds
Primarily invest in company shares and are designed for long-term capital appreciation.
Suitable for investors with higher risk tolerance and longer investment horizons.
Debt Mutual Funds
Invest in government securities, treasury bills, and corporate bonds.
Typically chosen by investors seeking relatively stable returns with lower volatility.
Hybrid Mutual Funds
Invest in a combination of equity and debt securities.
They aim to balance growth opportunities with risk management.
Index Funds
Track benchmark indices such as the Nifty 50 or Sensex.
They generally have lower expense ratios and follow a passive investment strategy.
ELSS Funds
Equity Linked Savings Schemes (ELSS) are equity mutual funds that provide tax benefits under Section 80C of the Income Tax Act, subject to prevailing tax laws.
These funds have a mandatory three-year lock-in period.
Step 5: Look Beyond Past Returns
Many investors select funds solely because they delivered exceptional returns in recent years.
However, past performance should never be the only deciding factor.
Instead, evaluate:
- Performance across multiple market cycles.
- Consistency of returns.
- Risk-adjusted performance.
- Portfolio quality.
- Investment philosophy.
A fund that consistently performs well over the long term may be more suitable than one that delivers occasional exceptional returns.
Step 6: Evaluate the Fund Manager and Investment Strategy
Behind every actively managed mutual fund is a professional fund manager.
Before investing, consider:
- Experience of the fund management team.
- Investment approach.
- Portfolio construction methodology.
- Consistency in executing the investment strategy.
Experienced fund managers supported by strong research teams can help navigate changing market conditions.
Step 7: Check the Expense Ratio
Every mutual fund charges a fee for managing investments, known as the expense ratio.
A lower expense ratio means a smaller portion of your investment goes toward fund management costs.
Although expenses should not be the only selection criterion, lower costs can positively influence long-term returns through the power of compounding.
Step 8: Review Portfolio Diversification
A well-diversified portfolio helps reduce concentration risk.
Before investing, examine whether the fund is diversified across:
- Industries
- Companies
- Market capitalizations
- Asset classes (where applicable)
Over-concentration in a few stocks or sectors may increase investment risk.
Step 9: Decide Between SIP and Lump Sum Investing
Mutual funds can be invested in through two primary methods.
Systematic Investment Plan (SIP)
SIPs involve investing a fixed amount at regular intervals.
Benefits include:
- Investment discipline.
- Rupee cost averaging.
- Long-term compounding.
- Reduced impact of market timing.
For many investors, SIPs are an effective way to build wealth gradually.
Lump Sum Investment
A lump sum investment involves investing a larger amount at one time.
This approach may be appropriate when investors have surplus funds and an investment strategy aligned with their financial goals.
Step 10: Read the Scheme Information Document
Before investing, review the Scheme Information Document (SID) and Key Information Memorandum (KIM).
These documents provide important details regarding:
- Investment objective.
- Risk factors.
- Asset allocation.
- Expense ratio.
- Exit load.
- Benchmark.
- Fund manager.
Understanding these documents helps investors make informed decisions.
Common Mistakes to Avoid
Many investors make avoidable mistakes that can impact long-term wealth creation.
Some of the most common include:
- Chasing recent top-performing funds.
- Ignoring investment goals.
- Investing without understanding risk.
- Frequently switching funds.
- Stopping SIPs during market corrections.
- Overlooking portfolio reviews.
A disciplined, goal-based approach generally delivers better long-term outcomes than reacting to short-term market movements.
Final Thoughts
Choosing the right mutual fund isn't about finding the scheme with the highest recent returns—it's about selecting investments that match your financial goals, investment horizon, and risk appetite.
Successful investing requires patience, consistency, and regular portfolio reviews.
At Moneytree Partners, we believe every investment should begin with a clear financial objective. Our goal-based investment approach helps investors build diversified mutual fund portfolios aligned with their unique financial aspirations, whether it's wealth creation, retirement planning, tax saving or achieving life goals.
Mutual Fund investments are subject to market risks. Please read all scheme-related documents carefully before investing. Past performance does not guarantee future returns.
Frequently Asked Questions (FAQs)
1. How do I know which mutual fund is right for me?
The right mutual fund depends on your financial goals, investment horizon, and risk tolerance. Choosing a fund that aligns with these factors is generally more important than selecting one based solely on recent performance.
2. Should I invest through SIP or lump sum?
Both approaches have their advantages. SIPs encourage disciplined investing and help manage market volatility through rupee cost averaging, while lump sum investments may be suitable when you have a substantial amount available for long-term investment.
3. Is past performance a good indicator of future returns?
Not necessarily. While historical performance provides useful information, it does not guarantee future results. Investors should also evaluate factors such as consistency, portfolio quality, fund management, and investment strategy.
4. How often should I review my mutual fund portfolio?
A portfolio review every 6 to 12 months or whenever there is a significant change in your financial goals or market conditions is generally considered a prudent approach.
5. Can I invest in more than one mutual fund?
Yes. Many investors build diversified portfolios by investing across different mutual fund categories based on their financial goals and risk profile. However, excessive diversification can make portfolio management more complex, so investments should remain aligned with a well-defined strategy.